
This article is credited to Money Management.
With tokenisation so far focused on banking, there are now opportunities coming to the fore for financial advisers as it offers the possibility to unlock access to alternative investments.
With tokenisation so far focused on banking, there are now opportunities emerging for financial advisers as it unlocks access to alternative investments.
In a white paper The Future of Alternatives from investment platform SILC, it discussed how tokenisation could improve access to private markets as well as the regulatory challenges it faces.
Tokenisation involves converting ownership of an asset into a digital representation, or token, recorded on a distributed ledger. These tokens can function as a new form of fund currency, replacing or augmenting traditional units in a managed investment scheme (MIS).
Consumers are expecting seamless access and real-time functionality when it comes to their retail and entertainment so it is unsurprising they will eventually want this option for their finances.
This particularly applies to private market assets where tokenisation could allow advisers to more efficiently manage and rebalance their exposure in assets that are illiquid and have high minimum investment thresholds.
“Just as streaming services transformed media consumption and digital wallets reshaped payments, tokenisation has the potential to redefine how investors interact with alternative assets,” the report said.
“For financial advisers, this transformation has important implications. Traditionally, advising on private market investments involved navigating complex subscription processes, limited liquidity and opaque reporting frameworks.
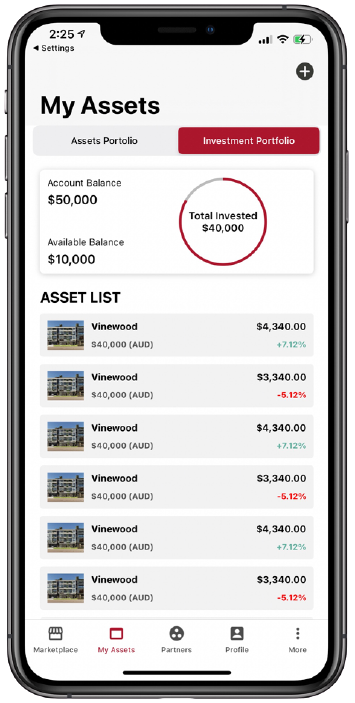
“Digital wallets, for example, may become a new interface for holding and managing fund exposures, while near-field communication (NFC) and mobile technologies could further streamline access and interaction.”
As well as this, the RBA’s Project Acacia explored how tokenised assets could operate within wholesale financial markets with testing across a range of asset classes. The report found tokenisation could also create new funding and liquidity channels by broadening investor access and improving transparency in wholesale markets.
The project’s experiments demonstrated opportunities to improve capital efficiency, reduce settlement frictions and counterparty risk, automate lifecycle management and provide access to 24/7 liquidity pools.
However, it highlighted several barriers to broader adoption, including legal and regulatory uncertainty, interoperability issues between digital platforms and coordination challenges across market participants.
This was echoed by the SILC white paper which singled out regulation around Know Your Customer and Anti-Money Laundering (KYC & AML) which is difficult to police when tracking the ownership of assets becomes difficult. Conducting KYC & AML processes is also hard to enact without a centralised framework to verify wholesale investor status.
“Current regulatory frameworks place the responsibility for KYC and AML compliance on a reporting entity (which may also hold an Australian Financial Services Licence), meaning that fund managers and platform operators must ensure that these obligations are met regardless of the underlying technology.
“This creates tension between the portability of tokens and the need for traceability of investors. While tokenisation enables assets to be transferred with ease, regulatory obligations require that each transfer be subject to identification and compliance checks.”