
Alternative assets are entering a new phase of growth and maturity, with governance, digital innovation and distribution models becoming just as important as investment performance, according to a new white paper released by The SILC Group.
The Future of Alternatives White Paper examines the structural changes transforming private markets and identifies four key themes expected to shape the next generation of alternative asset investing: the transformation of asset allocation, product differentiation, fund access with tokenisation and the future of distribution.
Drawing on global research from organisations including EY, PwC, Deloitte, McKinsey, ASIC and the World Economic Forum, the paper argues that alternative assets have moved from a peripheral allocation to a core component of modern portfolio construction. Institutional investors such as the Future Fund, AustralianSuper, Yale and Harvard have long embraced alternatives, and increasingly, wholesale and high-net-worth investors are following suit through more accessible structures such as evergreen and semi-liquid funds.
The report finds that the growing adoption of the Total Portfolio Approach is changing how investors think about portfolio construction, with private markets increasingly assessed for their contribution to overall portfolio outcomes rather than as standalone asset classes. At the same time, fund managers face growing pressure to differentiate through governance standards, operational excellence and investor experience as regulatory scrutiny increases and competition intensifies.
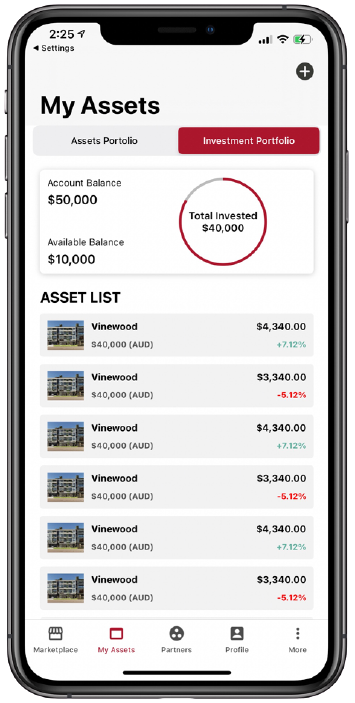
The paper also highlights the emerging role of tokenisation and digital infrastructure in broadening access to private markets, while identifying future distribution models as a critical competitive advantage for fund managers seeking to connect capital with opportunity.
For Fund Managers
The report highlights a clear imperative to embed governance, operational scalability and distribution considerations into product design from day one, rather than treating them as post-launch functions. Success will increasingly depend on demonstrating how strategies contribute to broader portfolio outcomes, supported by robust governance frameworks, transparent reporting and investor-centric structures.
For Distribution Teams, Placement Agents and Wealth Channels
The findings underscore the growing importance of portfolio-role messaging, adviser education and early-stage product collaboration. As private markets become more accessible and competitive, distribution professionals will play a more strategic role in shaping fund structures, aligning products with investor demand and communicating the value of alternatives in the context of total portfolio construction.
For AFSL Holders, Trustees and Responsible Entities
The report also notes that regulatory scrutiny is intensifying, with ASIC identifying private markets as an area of growing importance and highlighting conflicts of interest, valuation practices, governance and investor protection as key areas of focus. As private markets continue to expand into wealth and retail-adjacent channels, managers that can demonstrate strong governance, independent oversight and robust conflict-management frameworks are likely to be better positioned to meet evolving regulatory expectations and build investor confidence.
Koby Jones, Group Managing Director of The SILC Group, said the alternatives sector has reached an important turning point.
“Alternative assets are at an inflection point. While the sector is being tested by natural market forces and heightened regulatory scrutiny, a significant opportunity is emerging for a greater share of investors’ portfolios, driven by ongoing maturation in structuring, accessibility, governance and distribution,” said Jones.
Michelle Tay, Group Executive Director of The SILC Group, said success in the next phase of market evolution would require a more integrated approach.
“The next phase of alternatives will not be won by investment performance alone. It will be won by managers that integrate investment capability with institutional governance, liquidity architecture, digital infrastructure and distribution from the point of fund design,” said Tay.
According to The SILC Group, managers that embrace these structural shifts will be best positioned to capture the next wave of growth as private markets become increasingly accessible, transparent and interconnected.