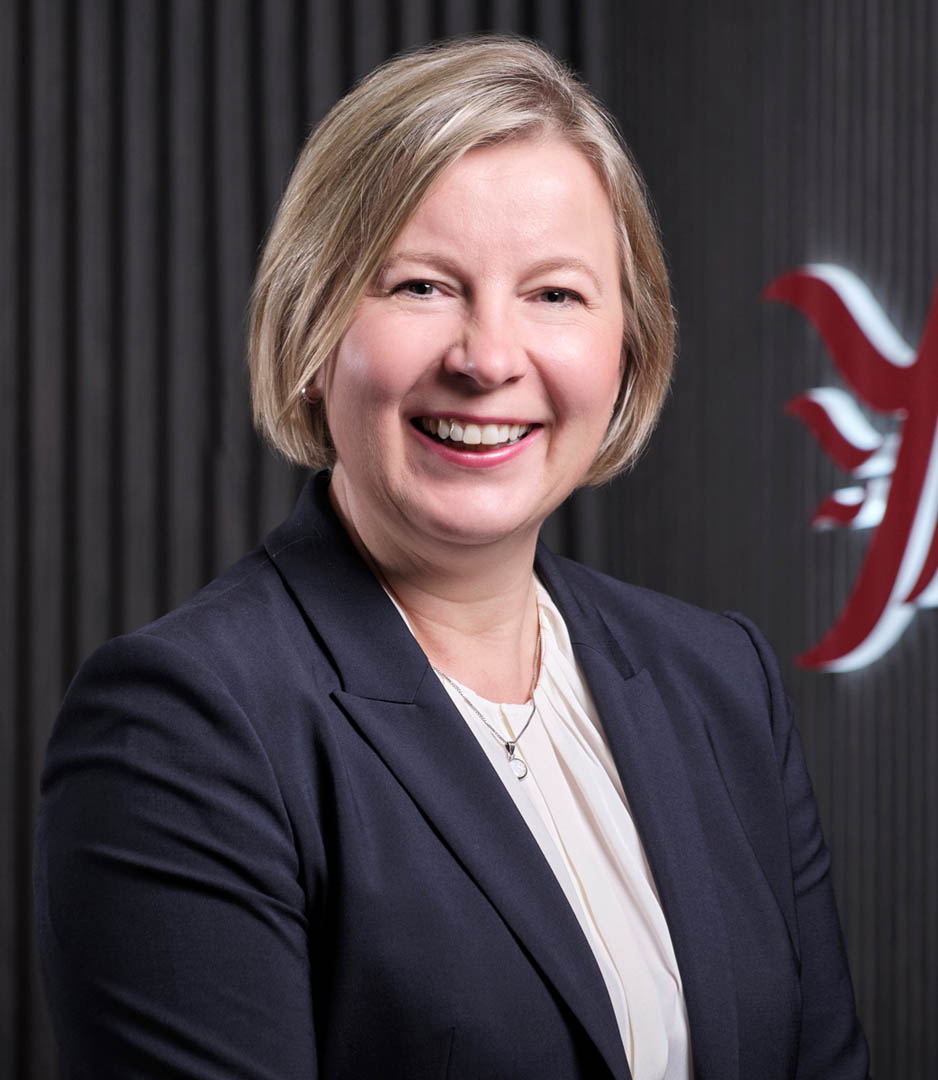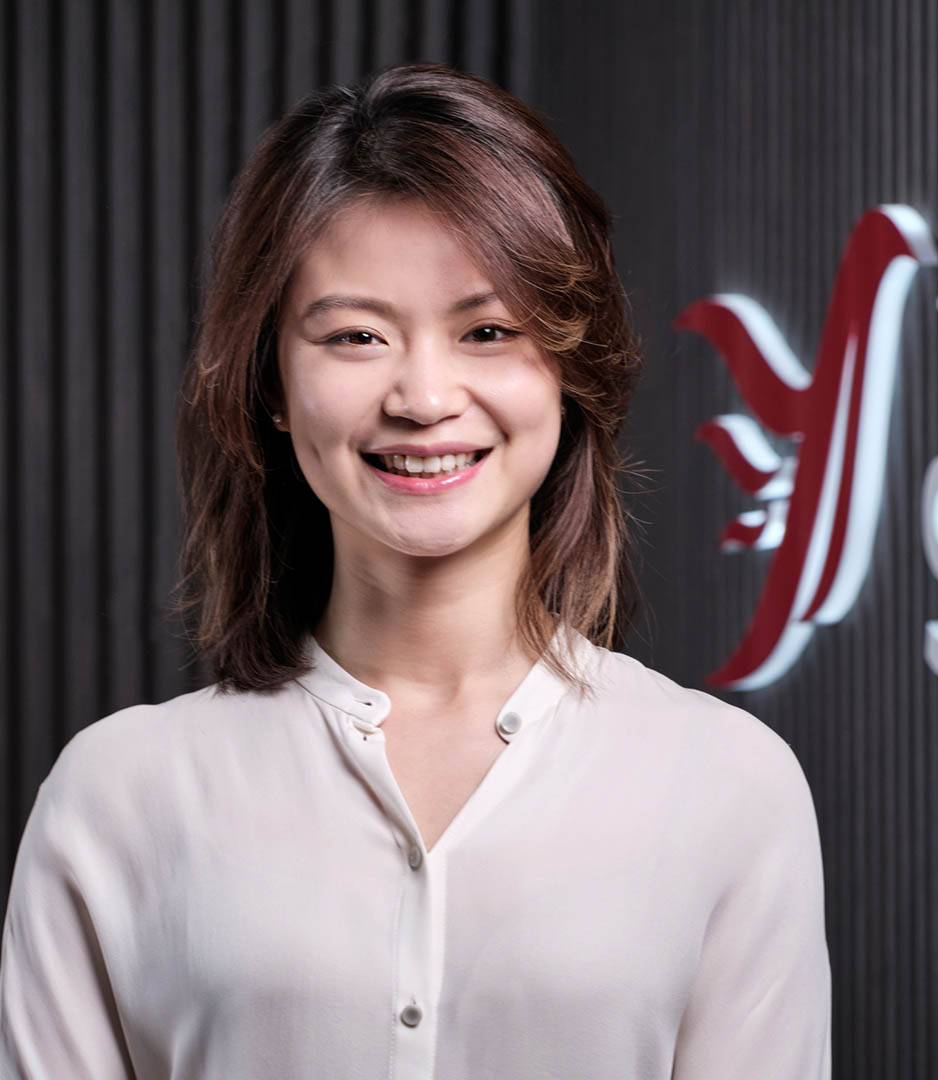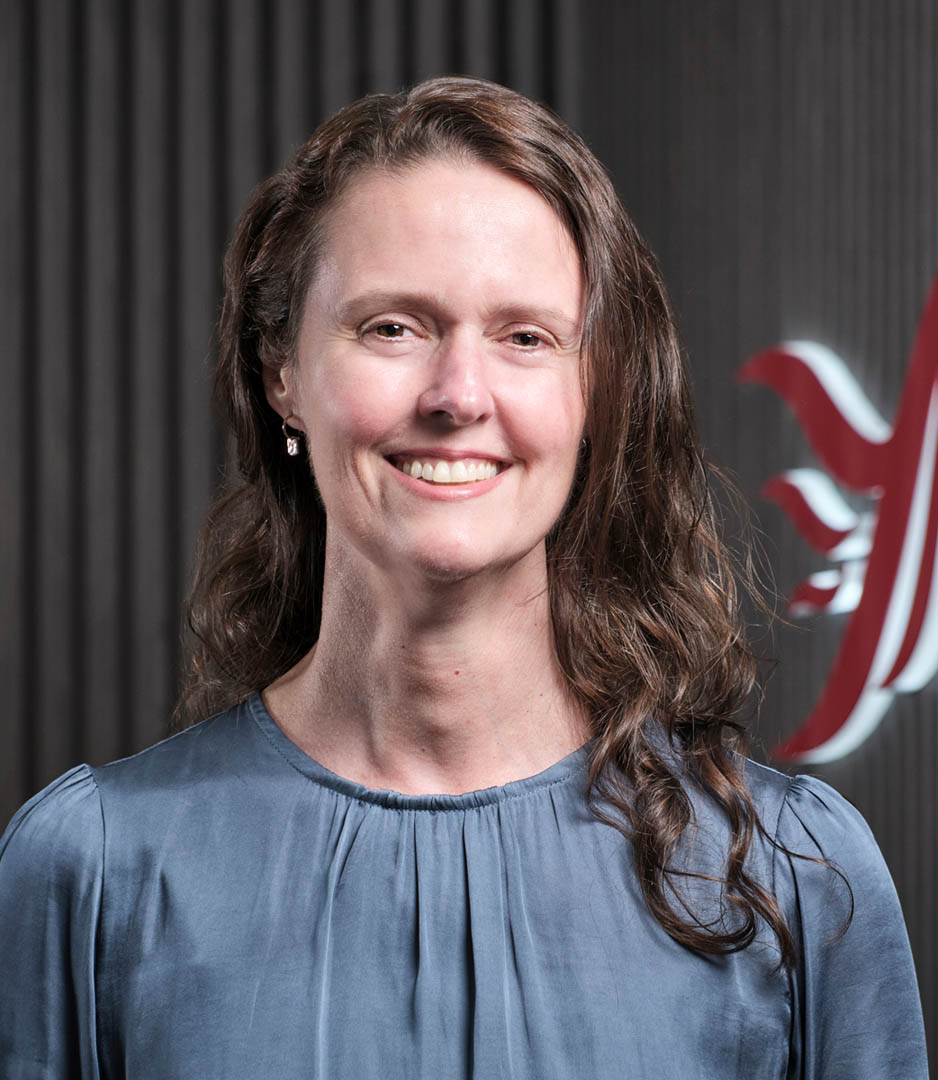

Michelle Tay is Group Executive Director and co-founder of The SILC Group, an Australian fund services firm established in 2011. In this Q&A, Michelle shares her perspective on the evolving role of fund trustees, what fund managers value in a trustee relationship and the philosophy that has shaped SILC since its founding.
Q. With ASIC increasing its focus on the robustness of private capital markets, can you clarify the role of fund trustees — and whether that role is changing?
ASIC’s increasing focus on governance, conflicts and risk management in private markets is an important and necessary development. In many ways it reinforces the role a trustee or responsible entity is meant to play in a fund structure – providing independent oversight around how a fund is established and operates.
Australia’s investment landscape has expanded significantly over the past decade. There is more capital, more funds and increasingly complex strategies as investors diversify away from public market volatility. Private capital funds alone have grown rapidly, reaching around $149 billion in the decade to March 2024 according to ASIC.
As more capital flows into private markets, governance around those structures becomes even more important.
Investors typically choose a fund based on the investment manager’s strategy and track record. The manager’s role is to run the portfolio and execute the investment strategy. Structurally and legally, however, they are not responsible for overseeing the governance of the fund itself.
That is where the trustee or responsible entity sits.
An independent trustee provides oversight around how the fund operates and ensures the structure continues to meet its obligations and operate in line with investor interests. It creates a layer of accountability that benefits both investors and fund managers.
In practice, most experienced managers recognise the value of that discipline in the structure. Clear separation of roles helps build confidence with investors and strengthens the integrity of the fund.
Q. How did SILC begin?
SILC started quite organically.
Koby Jones and I have known each other for more than 20 years and both came from financial services backgrounds, including time at ANZ. Koby spent much of his career in global markets and private wealth, while my experience was largely on the corporate and operational side of banking.

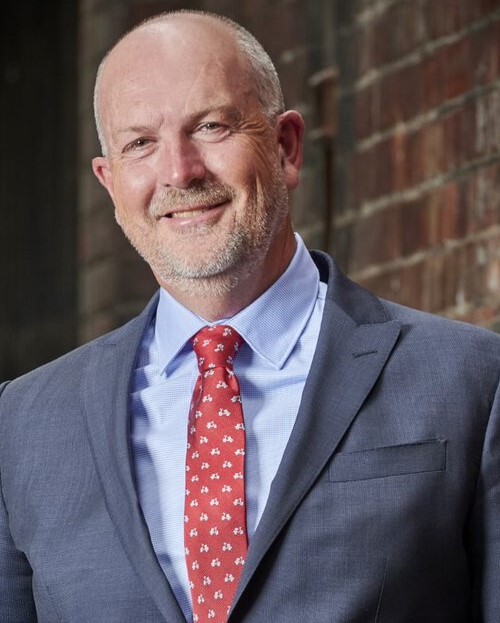
The SILC road. Koby Jones and Michelle Tay formed The SILC Group in 2011 and they bring complementary skills sets to the table.
In many ways we approach things from different perspectives. Koby tends to think in terms of the bigger picture and long-term strategy, while I focus more on the operational detail and execution. That balance has worked well for us. It also means we regularly challenge each other, which usually leads to more robust decisions. That dynamic has been important as the business has grown and the decisions have become more complex.
Starting SILC was very much a calculated gamble. We were both leaving established careers to build something from scratch, so the decision involved a fair amount of conviction.
Our original intention was to launch alternative investment funds ourselves.
As we started working through what it takes to establish those structures – licensing, trusteeship, administration and governance – we quickly realised how complex the ecosystem around funds really was. Establishing a fund meant coordinating multiple service providers, and the process could be fragmented and difficult for managers to navigate.
We did not set out to build a trustee business. It evolved as we began to understand what the industry actually needed.
Like most early-stage businesses, not everything went exactly as planned. There were ideas that did not work, approaches we had to rethink, and plenty of lessons along the way – both from our own experience and by observing where others in the industry struggled.
Looking back, that learning curve was one of the most valuable parts of building the business.
Rather than focusing solely on launching funds ourselves, we saw a larger opportunity to build the infrastructure around them – a platform that could support fund managers with the governance, licensing and operational framework required to establish and run funds properly.
Everything was built from the ground up. We bootstrapped the business and grew it steadily over time, which meant being disciplined about how we built the platform and the team.
That journey still shapes how we operate today.
Q. How does SILC work with fund manager clients?
Our role is to provide the infrastructure that allows fund managers to establish and operate their funds within a robust governance and operational framework.
That includes trusteeship, licensing and fund administration services. We work with managers launching new funds as well as those transitioning from another provider.
Where we differentiate ourselves is in how we work with clients.
Our approach is relationship-driven rather than volume-driven. We spend time understanding the manager’s strategy, operating model and growth plans so the structure and operational framework are aligned from the beginning.
Because we have been through the process of establishing fund structures ourselves, those conversations tend to be very practical. We understand where challenges can arise and where structures need to be carefully designed from the outset.
Over the past decade we have also seen funds through different market cycles and regulatory changes, which gives us a practical perspective on how these structures need to operate in the real world. The trustee role carries significant responsibility, so the structure has to work not just commercially but from a governance and regulatory perspective as well.
We also work closely with a network of Australian legal and accounting firms who support our clients across the lifecycle of a fund.
Q. What makes SILC stand apart?
Most managers who come to us have already worked with other providers, so they usually have a good sense of what works well and where the frustrations tend to sit. We also work with first-time fund managers who are establishing their first structure. In those situations, our role often involves working closely with them through the process and helping them understand the governance, regulatory and operational responsibilities that come with running a fund. Taking the time to support managers at that stage helps ensure the structure is set up properly from the beginning.
In many respects, what we do is not fundamentally different from other trustee or responsible entity providers. The regulatory role is broadly the same across the industry.
The difference sits in how the service is delivered and the level of care around the relationship.
SILC is privately owned with no external shareholders, no debt and no external pressure shaping how the business operates. Koby and I both remain actively involved in the business, which allows us to focus on long-term relationships with the managers we support.
At the same time, we recognise the importance of independent oversight. As the business has grown, we have brought in independent board members and established a compliance committee to ensure there are experienced people around the table who can challenge us and hold us accountable.
In our view, strong governance should start with the firm providing it.
Because we are owner-operators rather than employees of a large institution, we are directly invested in the success of the firm and the clients we work with.
A few things tend to stand out for clients.
Client Experience: Fund managers value service providers who are accessible and responsive. Our teams focus on understanding each client’s business and responding quickly when issues arise. Clients also have direct access to senior leadership.
Independence: Because the business is privately owned and focused solely on fund services, we do not have competing product lines or internal priorities that can sometimes arise within larger organisations.
Agility: Speed matters in this industry. We are structured to make decisions quickly and move efficiently when launching new funds or responding to investor queries. Establishing a new fund structure typically takes around eight weeks.
Technology: We have invested heavily in systems that improve both the manager and investor experience. One example is Australia’s first automated BPAY payment reconciliation system for investors, developed with The LAB Group and supported by Westpac.
Today SILC has a team of around 30 people, including an internal technology capability. Having that expertise in-house allows us to continually improve our systems and ensure the platform evolves with the needs of fund managers and investors.
The goal is to make the operational side of running a fund simpler and more predictable while maintaining strong governance and transparency.
Closing reflection
Building SILC has been a long journey. We started the business in 2011 and built everything from the ground up.
Over time we have grown the team, strengthened the platform and continued to invest in the infrastructure that supports our clients. Private markets will continue to evolve, and the infrastructure around them will need to evolve as well. Our focus is on continuing to build a platform that supports fund managers through that change.
What has remained constant is the philosophy behind the business. We are independent, founder-led and fully invested in what we are building.
When you own the business you are building, reputation and relationships matter – not just with fund managers, but with investors, regulators and the broader industry. That mindset continues to shape how we operate as SILC continues to grow.